Interest Rate Rise: What Should Property Buyers and Sellers Consider?
You may have found the right property, but would your mortgage still feel affordable if your monthly repayments increased? The latest interest rate announcement brings that question into focus for buyers planning their next move.
On 5 November 2026, the Bank of England announced an increase in its base rate from 3.75% to 4%, following a vote by its Monetary Policy Committee. Governor Andrew Bailey indicated that a further increase could be necessary if inflationary pressures persist. The Bank highlighted rising energy prices associated with the Middle East conflict as a factor behind its decision.
For those buying, selling or considering a remortgage, the announcement raises questions about borrowing costs, savings and how comfortably a property purchase fits within their finances.
What does the base rate mean for your mortgage?
The Bank of England’s base rate influences the rates lenders charge on mortgages. However, a base rate of 4% does not mean mortgages will be offered at 4%, or that every borrower’s repayments will increase immediately.
The impact depends on the mortgage terms. Some variable rates may rise, while existing fixed rates generally remain unchanged until the agreed fixed period ends.
What should buyers consider?
For buyers, affordability goes beyond mortgage approval. Monthly repayments should leave room for everyday spending, property maintenance and unexpected costs, including possible increases in repayments when rates change or a fixed deal ends.
When comparing mortgages, buyers should consider fees, the length of the deal and any early repayment charges alongside the headline rate. A mortgage adviser can help assess the available options.
If a purchase is already underway, buyers should check their mortgage offer’s conditions and expiry date with their lender or broker, particularly if completion is delayed, and keep their solicitor informed of any changes to funding.
Could there be a benefit for savers?
Higher interest rates may bring better returns on savings, potentially helping those building a deposit or holding funds for a future property purchase. However, banks and building societies do not necessarily pass on the increase automatically or in full, so the benefit will depend on the account and provider.
For prospective buyers, this creates a mixed picture. Savings may earn more interest, but the additional return may not outweigh higher mortgage costs. Buyers should therefore consider both sides when reviewing their budget and ensure their savings remain accessible when needed for the purchase.
What might this mean for sellers?
Sellers may feel the effects indirectly as buyers review their budgets. Higher borrowing costs could influence how much buyers are willing to offer or how long they need to arrange finance.
However, a rate rise does not automatically mean lower prices or slower sales. The impact will depend on the property, local demand and the buyer’s circumstances. Keeping informed about the buyer’s funding position can help sellers plan realistic timescales.
Could rates rise again?
Andrew Bailey has signalled that another increase may be needed, but further rises are not confirmed. The Bank has emphasised that future decisions will depend on the evidence. Its next interest rate decision is scheduled for 17 December 2026.
For buyers and sellers, the announcement is a reason to revisit financial assumptions and keep funding arrangements under review. The rate change itself does not alter the conveyancing process, but it may affect the financial decisions surrounding a move.
Chan Neill Solicitors will continue to monitor developments and share relevant updates. Our residential conveyancing team assists clients with the legal aspects of buying, selling and remortgaging property, working alongside their lenders and mortgage advisers throughout the transaction.

Standard Disclosure in Litigation: Do I Have to Disclose Documents That Harm My Case?
When involved in a dispute, you may expect to share documents that support your position. But what happens if an email, message or internal record undermines your case?
In civil litigation in England and Wales, standard disclosure can require parties to disclose both helpful and unfavourable documents. Understanding this obligation is essential when preparing for proceedings.
What is standard disclosure?
Disclosure means stating that a document exists or has existed. Inspection is the separate step of allowing another party to examine it or obtain a copy.
Where standard disclosure applies, CPR 31.6 requires parties to disclose:
- Documents on which they rely.
- Documents that adversely affect their own case.
- Documents that adversely affect another party’s case.
- Documents that support another party’s case.
- Documents required by a relevant practice direction.
Do I have to disclose documents that harm my case?
Yes. A document cannot be withheld simply because it is unhelpful.
For example, a supplier claiming that goods were delivered on time may hold an internal email acknowledging a delay. That email may need to be disclosed even though it undermines the supplier’s position.
The duty is owed to the court. Parties should give their solicitor potentially relevant documents, including unfavourable material, so that disclosure obligations can be assessed properly.
How extensive must the search be?
A reasonable search does not necessarily mean checking every historic file or electronic record. What is appropriate will depend on the dispute, including the likely importance of the documents and the time and cost involved in finding them.
For example, searches might focus on correspondence from a particular period or records held by people involved in the events. Any limits must be justified and explained in the disclosure statement.
Our litigation team can guide clients on where to look and how to carry out searches that meet their disclosure obligations.
Can any documents be protected from inspection?
Certain confidential communications may be protected by legal professional privilege. These include communications between you and your lawyer mainly for seeking or giving legal advice, and communications with third parties mainly for conducting existing or reasonably contemplated litigation.
Where privilege applies, you can generally withhold the contents from inspection, although the documents must still be identified appropriately in the disclosure list. An existing document does not become privileged simply because you send it to your solicitor.
What should parties remember?
The duty continues until proceedings conclude. If further documents falling within that duty come to light, the other parties must be notified immediately, normally through a supplemental disclosure list.
Our experienced litigation team can guide you through the disclosure process, helping you understand your obligations and identify the documents that need to be disclosed. Contact us today to discuss your matter.
This article explains standard disclosure under CPR Part 31. The applicable disclosure requirements depend on the proceedings and the court’s directions.
Home Buying and Selling Reforms 2026: What Could Change for Buyers and Sellers?
On 19 June 2026, the UK Government published its Home Buying and Selling Reform Roadmap, outlining proposed changes aimed at making residential property transactions in England, Wales and, in many respects, Northern Ireland faster, more transparent and less likely to fall through. The reforms are not expected to apply in Scotland, which has a distinct home-buying system.
The proposed reforms include requiring upfront property information through sales packs, introducing binding conditional contracts at an earlier stage and encouraging greater use of digital conveyancing. Many of these measures will require further consultation and legislation before they take effect. In this article, we explore the key proposals, how they differ from the current process and what they could mean for buyers and sellers.
Why Is the Government Reforming the Home Buying and Selling Process?
Buying or selling a property can be a lengthy and uncertain process. According to the Government, residential property transactions take approximately 120 days on average to complete after an offer is accepted, while around one in three transactions falls through before completion.
Delays can arise from property searches, title enquiries, mortgage arrangements and the late discovery of legal or structural issues. Furthermore, in England and Wales, an accepted offer is generally not legally binding until contracts are exchanged, meaning either party can usually withdraw before exchange without contractual penalties.
The proposed reforms aim to address these issues by making important property information available earlier, improving efficiency and providing greater certainty for buyers and sellers.
- Mandatory Upfront Property Information
One of the key proposals is the introduction of mandatory sales packs, which sellers would be required to have prepared before marketing their property. Sellers would retain overall responsibility for ensuring that the sales pack is prepared, although relevant professionals may be involved in gathering and verifying the information.
Currently, much of the legal investigation takes place after an offer has been accepted, including reviewing title documents, obtaining property searches and raising enquiries. Under the proposed reforms, this information would be made available earlier, allowing prospective buyers to make more informed decisions before submitting an offer.
The proposed sales packs are expected to include property searches and a property condition report, alongside other relevant information, such as title details and leasehold information where applicable. The precise contents of the sales pack remain subject to further development and guidance. This aims to identify potential issues earlier and reduce delays during the conveyancing process.
Mandatory sales packs have not yet been introduced. The Government intends to encourage their voluntary use before introducing legislation, when parliamentary time allows, to make them compulsory.
- Earlier Legally Binding Agreements
Another key proposal is the introduction of binding conditional contracts, which would make property transactions legally binding at an earlier stage.
Currently, in England and Wales, buyers and sellers generally become legally committed only when contracts are exchanged. Until then, either party can usually withdraw, even after significant legal costs have been incurred.
Under the proposed reforms, buyers and sellers would enter into binding conditional contracts earlier in the process. These contracts would be capable of including financial penalties where a party withdraws unnecessarily, although parties would still be able to withdraw in specified legitimate circumstances.
The Government has indicated that binding conditional contracts would not become mandatory until the proposed sales pack system has been embedded, ensuring that buyers have access to sufficient property information before making a legal commitment. This change would require future legislation.
- Greater Use of Digital Conveyancing
The Government also aims to modernise the conveyancing process through greater use of digital technology and improved information sharing.
In the longer term, the Government intends to legislate, when parliamentary time allows, to make digital property logbooks and sales packs standard features of property transactions. This would allow important property information to be stored and shared more efficiently.
During 2027 and 2028, the Government also intends to encourage the use of digital identity verification and Qualified Electronic Signatures, alongside improved data sharing between property professionals and measures to reduce duplication in anti-money laundering (AML) checks.
These changes aim to streamline administrative processes, reduce delays and improve efficiency throughout the conveyancing process. However, conveyancers will continue to play an important role in conducting legal due diligence and advising clients on potential risks.
- Improving Professional Standards for Estate Agents
The Government also proposes measures to strengthen professional standards and accountability within the property sector.
These include introducing a non-statutory Code of Practice setting out minimum standards for property agents and consulting on mandatory qualifications for estate and letting agents.
The reforms also aim to improve the quality and accuracy of information in property listings, helping prospective buyers make more informed decisions while increasing transparency and consumer confidence.
- Faster Access to Leasehold and Managed Estate Information
Delays in obtaining information from freeholders and managing agents can significantly affect residential property transactions, particularly when selling leasehold properties or properties on privately managed estates.
To address this, the Government intends to consult in 2027 and 2028 on legislation to implement the relevant provisions of the Leasehold and Freehold Reform Act 2024. Those provisions are intended to introduce maximum response periods and controls on charges for providing sales information, although they are not yet in force.
The proposed measures aim to make the process quicker, more affordable and more predictable for leaseholders and homeowners on privately managed freehold estates.
When Will the Reforms Take Effect?
The Government plans to introduce the reforms in stages, with some measures requiring further consultation and legislation.
- 2026 – Initial Measures: Introduce non-statutory guidance on property listings, encourage voluntary use of upfront sales packs and publish a Code of Practice for property agents.
- 2027–2028 – Further Development: Consult on mandatory qualifications for estate and letting agents, encourage the adoption of digital conveyancing tools and develop the proposed financial penalty structure for binding conditional contracts.
- Longer Term – Legislative Changes: Subject to parliamentary time, introduce legislation by the end of this Parliament to make sales packs mandatory, followed by binding conditional contracts once the sales pack system has been embedded.
There is currently no confirmed commencement date for the proposed mandatory sales packs or binding conditional contracts.
What Do the Reforms Mean for Buyers and Sellers?
For buyers, the proposed reforms could provide earlier access to important property information, helping them identify potential issues and make more informed decisions before submitting an offer.
For sellers, the changes could mean additional preparation before marketing a property, including obtaining searches and other relevant documents. While this may involve higher upfront costs, it could reduce delays and the risk of transactions falling through.
Both buyers and sellers may also face new legal obligations if binding conditional contracts are introduced. Understanding the terms of these agreements, particularly the circumstances in which a party may withdraw without penalty, will therefore be important.
Conclusion
The Government's Home Buying and Selling Reform Roadmap could bring significant changes to residential property transactions in England, Wales and, in many respects, Northern Ireland, with a greater focus on early disclosure, legal certainty and digital efficiency. However, many of the reforms remain proposals and will require further consultation or legislation before taking effect. Buyers and sellers should therefore not assume that any of these changes currently applies to their transaction.
At Chan Neill Solicitors, our Residential Conveyancing team assists clients with freehold and leasehold property transactions. Whether you are buying or selling a property, our team can guide you through the conveyancing process and help identify potential legal issues at an early stage.
For further information or legal assistance, please contact our Residential Conveyancing team.
This article is for general information purposes only and does not constitute legal advice.
Allotment and Share Transfer: What are the Differences?
Welcome to our Corporate & Commercial Explained series, where we explore key terms and concepts in corporate and commercial law and provide practical insights for businesses, shareholders and investors.
Shares in a company can change in a number of ways during the life of a business. A company may allot new shares to raise capital or bring in a new investor, or an existing shareholder may transfer their shares to somebody else.
Although allotment and transfer both involve changes to a company’s shareholding structure, they are different processes and can have different effects on the company and its shareholders.
What is an allotment of shares?
An allotment is where a company allots new shares to an existing or new shareholder, usually in return for payment or other consideration. The person receiving the shares becomes a shareholder once they are entered in the company’s register of members.
The key feature of an allotment is that new shares come into existence. The consideration is paid to the company, so an allotment is commonly used to raise equity finance. Once shares are allotted, the total number of shares in the company increases, and the company must notify Companies House.
An allotment can also affect the percentage ownership of existing shareholders. Where new shares are allotted to another person and an existing shareholder does not receive a proportionate number, their percentage shareholding will fall even though the number of shares they hold has not changed. This is commonly referred to as dilution, and it can affect a shareholder’s voting power and level of control.
Before allotting shares, a company will need to consider its articles of association, any shareholders’ agreement, whether the directors have the necessary authority to allot shares under the Companies Act 2006, and whether existing shareholders have statutory pre-emption rights. Statutory pre-emption rights generally apply where equity securities are allotted for cash, giving existing shareholders the opportunity to subscribe for the new securities in proportion to their existing holdings. They can be excluded by a private company’s articles or disapplied by shareholder resolution, so it is important to check what applies to the company in question.
What is a transfer of shares?
A share transfer occurs when an existing shareholder sells or gives some or all of their shares to another person, who may already be a shareholder or may become one as a result.
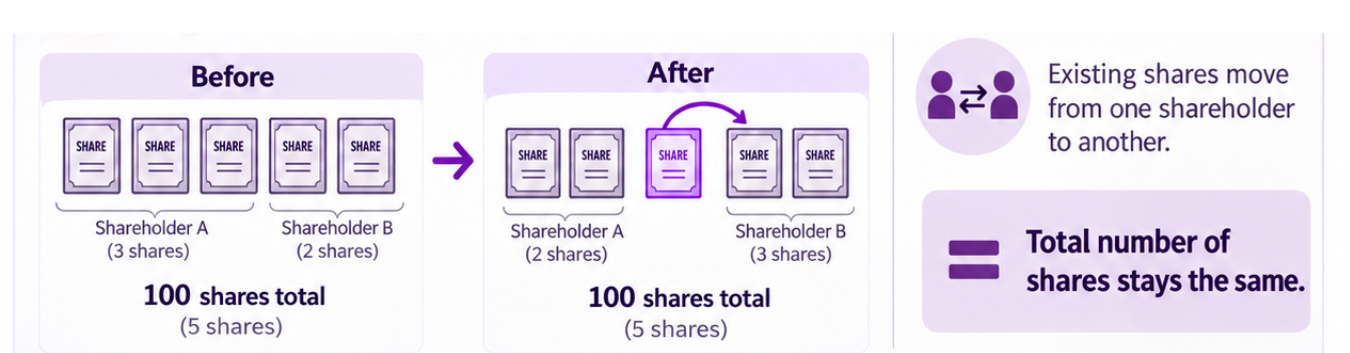
Unlike an allotment, no new shares come into existence, and the total number of shares stays the same. Where shares are sold, the price is paid to the transferring shareholder rather than to the company.
A transfer is usually effected by a stock transfer form, and the company must register the transfer (or give notice of refusal) within two months of receiving it. The articles and any shareholders’ agreement should also be checked before a transfer, as they may restrict transfers or give existing shareholders a right of first refusal.
Although the total number of shares does not change, a transfer can have a significant effect on ownership and control. For example, one shareholder may increase their percentage by acquiring shares from another.

What is the main difference?
The simplest way to distinguish the two is to consider what is happening to the shares. With an allotment, the company allots new shares and the total number increases. With a transfer, existing shares move from one holder to another and the total remains the same.
Either process can affect ownership structure, percentage interests and the balance of voting control. In both cases, changes in a person’s shareholding or voting rights may require the company’s PSC register and Companies House filings to be updated, particularly where the change takes the person above or below the more than 25% threshold.
How can we help?
The appropriate process will depend on the circumstances of the company and its shareholders. Companies should consider their articles of association, any shareholders’ agreement and the requirements of the Companies Act 2006 before making changes to their share structure. Please contact us to discuss your situation.
This article is for general information only and does not constitute legal advice. Specific advice should be sought before taking any action.
Coming next: Can a company buy back its own shares, and what are the effects of a share buy-back?
Understanding Your Conveyancing Documents - What Is a TR1 Form and Why Do You Need to Sign It?
As part of our Conveyancing Series, we explain some of the key documents you may come across during a property transaction, helping buyers, sellers and property owners better understand what they are being asked to sign and why it matters.
If you are buying, selling or transferring a property in England and Wales, one document you may be asked to sign is a TR1 form.
The TR1 is an important part of the conveyancing process. It is the transfer deed used to transfer the whole of a registered title from one party to another and forms part of the process of updating the registered ownership of the property at HM Land Registry.
You may also come across a TP1 form during the conveyancing process. Although it is similar to a TR1, it is used where only part of a registered title is being transferred, rather than the whole title. We will explain TP1 forms in more detail in the next article in our Conveyancing Series.
Read Conveyancing Documents Series 1 – Title Guarantee
Read Conveyancing Documents Series 2 – Reserve Funds
What Is a TR1 Form?
A TR1, formally known as a “Transfer of Whole of Registered Title”, is an HM Land Registry form used where the whole of an existing registered title is being transferred.
The person transferring the property is known as the transferor, while the person receiving the property is the transferee.
In a typical property sale:
- Seller = Transferor
- Buyer = Transferee
The form records important information about the transfer and is later used as part of the application to update the registered ownership at HM Land Registry.
The same TR1 form can be used whether the parties involved are individuals or companies, although different supporting information may be required.
When Is a TR1 Required?
A TR1 is most commonly used when a property is sold from one owner to another.
However, it can also be required where ownership changes without a conventional sale, including certain transfers of equity.
TR1 in a Property Sale
In a normal property sale, the TR1 is the deed used to transfer the registered title from the seller to the buyer.
It is important to distinguish the TR1 from the contract for sale.
The contract sets out the terms agreed between the buyer and seller. Once contracts are exchanged, the transaction becomes legally binding.
The TR1 has a different purpose. It is the legal transfer deed that gives effect to the change in ownership as part of the completion and registration process.
The TR1 may be signed before completion so that it is ready for the transaction to complete. Your solicitor or conveyancer will advise you when and how it should be signed.
TR1 in a Transfer of Equity
A TR1 may also be used in a transfer of equity, for example where:
- an existing co-owner is removed from the title;
- a new co-owner is added;
- a property moves from sole ownership into joint ownership; or
- a jointly owned property is transferred into one person’s sole name.
Transfers of equity can arise following changes in family circumstances, separation, marriage, financial arrangements or other ownership changes.
If there is a mortgage over the property, the lender’s consent may also be required before the transfer can proceed.
What Information Is Included in a TR1?
Although the TR1 is relatively short, it contains important information about the property and the transfer.
- Title Number and Property Address
- Transferor and Transferee
- Consideration – usually the purchase price, although the transfer may also be made by way of gift or for another form of consideration.
- Full or Limited Title Guarantee – the TR1 records the type of title guarantee being given by the transferor, which affects the promises made regarding ownership of the property and third-party interests. We have explained the difference between full and limited title guarantee in an earlier article in our Conveyancing Series.
- Joint Ownership – where there is more than one transferee, the TR1 can record how the buyers intend to hold their beneficial interest in the property.
- Additional Provisions – the form may also include covenants or other obligations agreed between the parties.
Who Needs to Sign the TR1?
All transferors will normally need to sign the TR1. A transferee may also need to sign where they are entering into certain covenants, declarations or other obligations.
Where an individual signs the TR1 as a deed, their signature will usually need to be witnessed. It is important to follow your solicitor or conveyancer’s signing instructions carefully and not date the document unless specifically asked to do so, as incorrect execution can cause delays.
What Happens After the TR1 Has Been Signed?
Once the TR1 has been properly signed, it will usually be held by the solicitors or conveyancers until completion.
On the agreed completion date, the purchase monies are transferred and the transaction completes. The TR1 is then dated with the completion date.
Following completion, the buyer’s solicitor or conveyancer will usually deal with the post-completion requirements, which may include:
- submitting any required Stamp Duty Land Tax return and payment to HM Revenue & Customs;
- applying to HM Land Registry to register the new owner;
- submitting the TR1 and supporting documents;
- paying the relevant Land Registry fee; and
- registering any new mortgage over the property.
HM Land Registry will then process the application and update the register to show the new owner or owners.
Processing times can vary depending on the nature and complexity of the application, so registration may not be completed immediately after the purchase itself has completed.
Do I Need a Solicitor to Complete a TR1?
It is not always legally necessary to instruct a solicitor or licensed conveyancer to complete a TR1. However, transferring property ownership can involve restrictions, mortgages, covenants, tax issues and other registration requirements.
A solicitor or conveyancer can prepare or review the TR1, ensure it is signed correctly and deal with the registration process. Errors can lead to Land Registry requisitions and delays.
How Can Our Conveyancing Team Help?
Chan Neill Solicitors LLP’s Conveyancing team advises on a wide range of property transactions, including sales, purchases and transfers of equity.
Our multilingual team can guide you through the conveyancing process, explain the documents you are asked to sign and assist with the registration requirements following completion.
If you require assistance with a property transaction or transfer of ownership, please contact our Conveyancing team to discuss how we may assist.
Family law - Are Pensions Built Up Before Marriage Protected?
Dividing assets on divorce involves considering both the wealth available and what each person needs for the future. Pensions can form a substantial part of that picture, particularly where the parties are approaching retirement. Rights built up before marriage may remain non-matrimonial, but they are not automatically beyond the reach of a financial claim.
This article examines BS v HC [2026] EWFC 20 (B) and what it shows about pre-marital pensions, matrimonialisation and the “add-back” of gifts made after separation.
How assets are divided on divorce
In England and Wales, courts consider all the circumstances, including the parties’ financial resources, needs, contributions and the length of the marriage. The welfare of any minor child is the court’s first consideration.
Equal sharing is the usual starting point for matrimonial property, with financial and domestic contributions valued equally. However, the outcome must reflect the parties’ circumstances and needs.
Pre-marital assets, inheritances and external gifts are generally non-matrimonial. In Standish v Standish [2025] UKSC 26, the Supreme Court confirmed that the sharing principle applies only to matrimonial property, although other assets may be used to meet needs or become matrimonial if treated as shared over time.
Pensions fall within the same framework, but the distinction can be harder to apply. Rights built up during marriage are generally matrimonial, yet one pension may also contain earlier rights and remain untouched until retirement. The court may therefore need to determine the matrimonial portion and whether any earlier rights later became shared. These questions were central to BS v HC.
How the court approached the pensions in BS v HC
In BS v HC [2026] EWFC 20 (B), the parties began living together and married in 2009 before separating in 2024. At the hearing, the husband’s pensions were worth about £3.06 million, compared with the wife’s £35,000. Much of his pension provision originated before the relationship but had grown considerably during it.
The parties proposed different methods of calculating the matrimonial portion. Applying Hart v Hart [2017] EWCA Civ 1306, HHJ Hess adopted a broader assessment because an exact mathematical division was difficult. He assessed 55% as matrimonial and 45% as non-matrimonial, based on the particular evidence rather than a fixed formula.
The court then considered whether the earlier portion had become matrimonialised. This could occur where the spouses intended to use the pension together in the future and one spouse relied on that intention to their detriment. Although the wife relied on a 2013 assurance that they would share everything, pensions were not mentioned. Her argument therefore failed.
Nevertheless, she could still share the matrimonial portion. She received 27.5% of the husband’s Quilter SIPP, broadly half of the 55% assessed as matrimonial. The overall award met her needs, so no further provision was made from the non-matrimonial portion.
Add back arguments about gifts after separation
In BS v HC, the wife requested an add-back of £102,330 for payments the husband made to his adult children after the relationship had broken down. An add-back is an exceptional adjustment that treats money already spent or given away as if it still formed part of the disposing spouse’s assets. It does not recover the money from the recipient.
The wife argued that, without an adjustment, she would effectively bear half the cost of the gifts. The court refused her request because the payments did not meet the high threshold of wanton or reckless spending intended to reduce her share. Although one gift came close, the court found that arguments concerning the wife’s own spending neutralised the position.
Why the circumstances matter
A long marriage does not automatically make every earlier asset matrimonial. Equally, identifying part of a pension as non-matrimonial does not prevent the court from considering it where necessary to meet retirement needs. The Pensions Advisory Group’s 2024 guidance, known as PAG2, recognises that needs often influence pension outcomes.
The court will consider how the pension developed, how the parties treated it and the resources each person will need. As BS v HC shows, pension apportionment is not purely mathematical but depends on the evidence and circumstances of each case.
How our Family Law team can help
Chan Neill Solicitors LLP’s experienced Family Law team advises on divorce and related financial matters. We can explain how pensions and other assets may be treated, assist with financial disclosure, address concerns about spending or gifts, and help with negotiations, consent orders and court proceedings. Where required, specialist pension evidence can be considered as part of the wider settlement.
Our trilingual team provides clear, practical advice in English, Mandarin and Cantonese. If you have concerns about your pension, financial position on divorce or another family law matter, please contact us to discuss how we may assist.
Family Law Case Study 2: Financial Remedy Proceedings Involving Overseas Assets and Financial Disclosure
Financial Remedy Proceedings Following a Long Marriage Successfully Resolved at Financial Dispute Resolution
Financial remedy proceedings following the breakdown of a long marriage can become particularly complex where the parties’ assets extend across multiple jurisdictions and there are concerns about whether full financial disclosure has been provided.
Chan Neill Solicitors LLP represented a client in financial remedy proceedings following the breakdown of a long marriage. The case involved assets in the UK and overseas, including property in China and a shareholding, together with significant issues surrounding financial disclosure and valuation evidence.
The matter ultimately concluded successfully by agreement following a Financial Dispute Resolution (FDR) hearing.
The background
This case arose from the breakdown of a long marriage involving a couple with two children. Following the separation, divorce proceedings were issued and the matter progressed into financial remedy proceedings. The assets in question included the former family home in Southwick, property interests in Foshan, Guangdong Province, China, and a company-owned property in Brighton, East Sussex. The case developed into a complex financial dispute concerning asset division, the adequacy of financial disclosure, and property valuation, requiring specialist family law and financial remedy expertise.
The Central Issue: Financial Disclosure
A central issue in the case was our client’s concern that the Respondent’s financial disclosure was incomplete. This included concerns about missing bank statements and other financial documents. The matter also raised potential third-party issues, including whether third-party disclosure should be sought and whether a third party should be joined to the proceedings. Property valuation was another important issue, and the court ordered the parties to jointly instruct a single joint expert to prepare an independent valuation report.
Our Approach
Our Family Law team developed and pursued a detailed disclosure strategy, identifying gaps in the Respondent’s financial information and investigating overseas assets, company interests and potential third-party involvement.
We worked closely with counsel and experts, coordinated valuation evidence, prepared the case for the FDR hearing and advanced settlement proposals on our client’s behalf.
This thorough preparation helped place our client in a strong position for negotiations, and the matter was successfully resolved by agreement following the FDR.
Cross-Border and Evidential Challenges
A key challenge was addressing ongoing concerns about the completeness of the Respondent’s financial disclosure, including missing bank statements, unexplained transactions and inconsistencies in the financial information provided.
The case was further complicated by assets across the UK and China, competing valuation evidence, tax and fund repatriation issues, and questions concerning possible third-party interests and beneficial ownership.
Outcome
The financial remedy proceedings were successfully resolved by agreement following the FDR hearing, avoiding the need for a contested final hearing.
The parties agreed a full and final consent order bringing their financial claims arising from the marriage to an end. The agreement included the husband vacating the family home and removing his Home Rights Notice, with a clean break between the parties.
How we can help:
Chan Neill Solicitors LLP’s Family Law team has extensive experience advising on a wide range of family law matters, including divorce, financial remedy proceedings, child arrangements and complex cases involving overseas assets and cross-border issues.
Our trilingual team provides clear, practical and tailored advice, with an understanding of the sensitive personal, financial and international issues that can arise in family disputes.
If you have concerns about financial disclosure, overseas assets or any other issue arising from divorce or separation, or require advice on another family law matter, please contact our Family Law team to discuss how we can assist.
What amounts to travel disruption in COVID-19 related Long Residence cases?
The legal framework and the Home Office’s approach
The COVID-19 pandemic may have ended as a global emergency, but its impact continues to surface in UK immigration cases, particularly those involving applications for settlement based on ten years’ lawful residence, commonly known as the Long Residence route.
For many applicants, difficulties arise where the total allowable absences of 548 days have been exceeded as a result of lengthy trips abroad during the pandemic. In such cases, applicants may seek to have COVID-19-related absences disregarded on the basis of “travel disruption”.
However, what exactly amounts to travel disruption?
The answer is not always straightforward. Whilst the Immigration Rules expressly recognise, in paragraph CR 3.4 of Appendix Continuous Residence, “travel disruption due to natural disaster, military conflict or pandemic”, they do not define the term “travel disruption”.
The Home Office guidance to caseworkers offers little further clarity
“You should confirm, using publicly available and credible sources, that there was a natural disaster, military conflict or pandemic at the relevant time which caused travel disruption. The Foreign and Commonwealth Office travel advice pages on GOV.UK may be helpful to confirm this. You should normally expect the applicant to provide evidence of how their ability to travel to the UK was affected, for example, evidence of disruption to planned travel arrangements.”
In practice, the key question is whether the applicant’s prolonged absence resulted from circumstances outside their control rather than a voluntary decision to remain abroad.
This distinction is often decisive.
The clearest example of travel disruption involves an applicant who purchased a return ticket to the UK but was unable to travel because the flight was cancelled, rescheduled, or otherwise disrupted by pandemic-related restrictions. Documentary evidence of cancelled flights, airline notifications, border closures, or travel bans can provide compelling proof that the applicant intended to return but was prevented from doing so.
This scenario frequently arose in cases involving international students who returned to their home countries at the beginning of the pandemic following guidance from their educational institutions, only to discover that they were unable to return to the UK because of airline cancellations, lockdowns, or entry restrictions.
However, the reality of the pandemic was often more complicated.
In the early stages of COVID-19, international travel became highly unpredictable. Flight routes were suspended with little notice, entry requirements changed rapidly, and ticket prices increased significantly. Not every individual was in a position to purchase a return ticket before departing the UK.
For such applicants, demonstrating disruption to planned travel arrangements may be considerably more challenging. The challenge can be further compounded where the applicant was able to continue working or studying remotely from abroad. In those circumstances, the Home Office may be tempted to conclude that the applicant simply chose to remain overseas.
Our Immigration Team has represented clients seeking settlement under the Long Residence route in cases of varying complexity. For tailored advice and assistance, please do not hesitate to contact our Immigration Team.
This article is provided for general information only. It is not intended to be and cannot be relied upon as legal advice or otherwise. If you would like to discuss any of the matters covered in this article, please contact us using the contact form or email us on reception@cnsolicitors.com
Parent of a Child Student Visa UK: Complete Guide for Parents
The Parent of a Child Student visa allows one parent to live in the UK while caring for a child who is studying at an eligible independent school under the Child Student visa route.
This visa is designed for international parents whose child is aged between 4 and 11 and is attending an independent fee-paying school in the UK. It is a temporary immigration route and does not provide a direct route to settlement.
This guide explains who can apply, the financial requirements, visa restrictions, extensions and common application issues.
What is a Parent of a Child Student Visa?
A Parent of a Child Student visa enables a parent to come to or remain in the UK to care for their child during the child’s studies.
The child must:
- hold, or be applying for, permission under the Child Student route;
- be aged between 4 and 11 on the date of the parent’s application; and
- attend, or intend to attend, an independent fee-paying school that meets the requirements of the Child Student route.
The parent must intend to live with the Child Student during their stay in the UK. The school must not be a state school or academy.
Who Can Apply?
You may be eligible for a Parent of a Child Student visa if:
- you are aged 18 or over;
- you are the parent of a child who has, or is applying for, a Child Student visa;
- your child is aged between 4 and 11 when you apply;
- your child is attending an eligible independent fee-paying school;
- you intend to live with and care for your child in the UK;
- the child’s other parent is not living in the UK and is not seeking to come to the UK;
- you have sufficient funds to support yourself and any additional children in your care; and
- you do not intend to make the UK your main home.
The application can be made from outside the UK or, where permitted, from inside the UK to extend existing permission. The applicant must obtain entry clearance before travelling to the UK if applying from overseas
Can both parents accompany the child?
No. Only one parent can hold permission under the Parent of a Child Student route.
The child’s other parent must not be in the UK or seeking to come to the UK. Separation, divorce or an assertion that one parent has sole responsibility does not, by itself, remove this requirement under the Parent of a Child Student rules.
The other parent may be able to visit the UK separately, provided they satisfy the requirements of the relevant visitor route. They cannot use a visitor visa to live in the UK or to accompany the child on a long-term basis.
Can other children accompany the parent?
Additional children may be able to accompany the parent if they also hold, or are applying for, permission under the Child Student route.
Other family members cannot be included as dependants under the Parent of a Child Student route. They may need to consider a separate immigration category, such as the visitor route, if they wish to come to the UK temporarily.
Financial Requirements
The parent must demonstrate that they can support themselves and any additional children without relying on public funds.
Where the relevant exemption does not apply, the parent generally needs to show:
- £1,560 for each month of the intended stay, up to a maximum of nine months; and
- £625 for each month, up to a maximum of nine months, for each additional child who will be under the parent’s care in the UK.
The applicant must also have sufficient funds to maintain their main home outside the UK. This is in addition to the funds required for living expenses in the UK.
The financial evidence will usually need to show that the required funds have been held for the prescribed 28-day period, subject to the evidential requirements in Appendix Finance.
Some applicants may not need to provide financial evidence. For example, an applicant applying to extend permission who has been lawfully in the UK for at least 12 months may satisfy the financial requirement without showing funds.
Restrictions Under This Visa
A Parent of a Child Student visa is subject to significant restrictions. The visa holder cannot:
- undertake paid or unpaid work;
- establish or run a business;
- study;
- access public funds; or
- make the UK their main home.
The purpose of the route is to enable the parent to care for the Child Student temporarily. It is not intended to provide a general right to work, study or settle in the UK.
Does This Visa Lead to Settlement?
The Parent of a Child Student route is not itself a settlement route, and time spent on it does not directly qualify the parent for indefinite leave to remain under this category.
However, lawful residence on many immigration routes may contribute towards the 10-year continuous lawful residence period under the long-residence rules. Eligibility depends on the applicant’s complete immigration history, permitted absences, continuity of residence and the rules in force at the time of application.
Applicants should obtain tailored advice before relying on time spent as a Parent of a Child Student when planning a long-residence application.
Common Practical Issues
Applicants should take particular care with:
- proving the parent-child relationship;
- confirming that the child has, or is applying for, Child Student permission;
- demonstrating that the school is an eligible independent fee-paying school;
- explaining the arrangements involving the child’s other parent;
- providing financial evidence in the correct form and covering the required period;
- demonstrating that the parent will live with and care for the child;
- showing that the UK will not become the parent’s main home; and
- ensuring that accommodation and care arrangements are suitable.
An application may be delayed or refused if the evidence is incomplete, inconsistent or does not address the specific requirements of Appendix Parent of a Child Student.
How We Can Help
At Chan Neill Solicitors, our immigration team advises international families on UK education-related immigration routes.
We can assist with:
- assessing eligibility for a Parent of a Child Student visa;
- reviewing the child’s Child Student visa and school arrangements;
- preparing the parent’s application and supporting evidence;
- advising on financial and accommodation documentation;
- addressing issues concerning the child’s other parent;
- advising on extensions and future immigration options; and
- liaising with the Home Office where appropriate.
If you are considering accompanying your child to the UK, our immigration solicitors can advise on the requirements and help you prepare a properly documented application.
Directors’ Duty to Exercise Independent Judgment: Understanding Section 173 of the Companies Act 2006
The Directors’ Duties Series – Part 3
This article is part of our directors’ duties series. It examines section 173 of the Companies Act 2006, which requires directors to exercise independent judgment. Directors may consider the views of colleagues, shareholders and professional advisers, but the decision must ultimately be their own.
What Does the Duty to Exercise Independent Judgment Mean?
Section 173 requires directors to assess the available information and reach their own conclusion rather than subordinate their powers to another person’s wishes. The duty is owed to the company, not to the shareholder, investor or other person who may have appointed or influenced them.
In practice, directors should not:
- automatically follow instructions from a shareholder, investor or parent company;
- allow a dominant director or founder to make decisions on their behalf;
- accept professional advice without applying their own judgment; or
- delegate a matter without retaining appropriate oversight.
Independent Judgment Does Not Mean Acting Alone
The duty does not require directors to make decisions in isolation. They may seek advice, consider the views of others and reach the same conclusion, provided that they form their own view. Directors may also question or challenge fellow board members, but must continue to act within the company’s constitution and collective decision-making process. Independent judgment does not allow them to bypass a properly made board decision.
How Does the Duty Apply to Nominee Directors and Group Companies?
Nominee directors appointed by a shareholder, investor or lender may take the appointing party’s views into account. However, they must not treat those views as binding or automatically place that party’s interests above those of the company.
The same principle applies within a corporate group. A subsidiary’s director must consider the subsidiary’s own position rather than simply adopt the parent company’s instructions. Competing interests may also engage the separate duties concerning conflicts and declarations of interest.
Delegation and Exceptions Under Section 173
Directors do not have to carry out every task personally. Where permitted by the company’s constitution, they may delegate work to another person or committee. However, they should choose someone suitable, maintain appropriate oversight and intervene if concerns arise.
Section 173 also recognises that a director’s duty of independent judgment does not prevent the company from entering into binding agreements. Directors must exercise their independent judgment when deciding whether the company should enter into an agreement. Once it has been validly entered into, complying with it later will not breach section 173 simply because it limits the board’s future choices.
This principle was recognised in Fulham Football Club Ltd v Cabra Estates plc [1994] 1 BCLC 363. The directors had exercised their judgment when approving the agreement, so complying with it later did not mean that they had surrendered their independence.
The directors must still comply with all their other statutory duties when delegating work or approving an agreement.
Practical Considerations for Directors
Directors should review the relevant information, ask questions, identify any conflicts or external pressure, ensure that delegation is properly authorised and record the reasons for important decisions.
Professional advice may be particularly valuable where there are competing interests, shareholder pressure or uncertainty about a director’s authority. However, responsibility for the final decision remains with the director.
What Happens if the Duty Is Breached?
A breach may expose a director to a civil claim by the company. Depending on the circumstances, remedies may include an injunction, rescission of a transaction, an account of profits or financial compensation. A shareholder may also seek permission to bring a derivative claim on the company’s behalf, while serious misconduct may contribute to disqualification proceedings.
The same conduct may breach several duties, including those concerning acting within powers, promoting the company’s success, exercising reasonable care, skill and diligence and avoiding conflicts of interest.
How Can We Help?
When board disagreements, shareholder pressure or competing group interests arise, our experienced solicitors advise companies, directors and shareholders on corporate governance and alleged breaches of directors’ duties. We can also review company articles, shareholders’ agreements and proposed transactions before disputes arise.
Our multilingual team can assist clients in English, Mandarin and Cantonese. Contact Chan Neill Solicitors LLP today for advice tailored to your circumstances.
This article is for general information only and does not constitute legal advice.