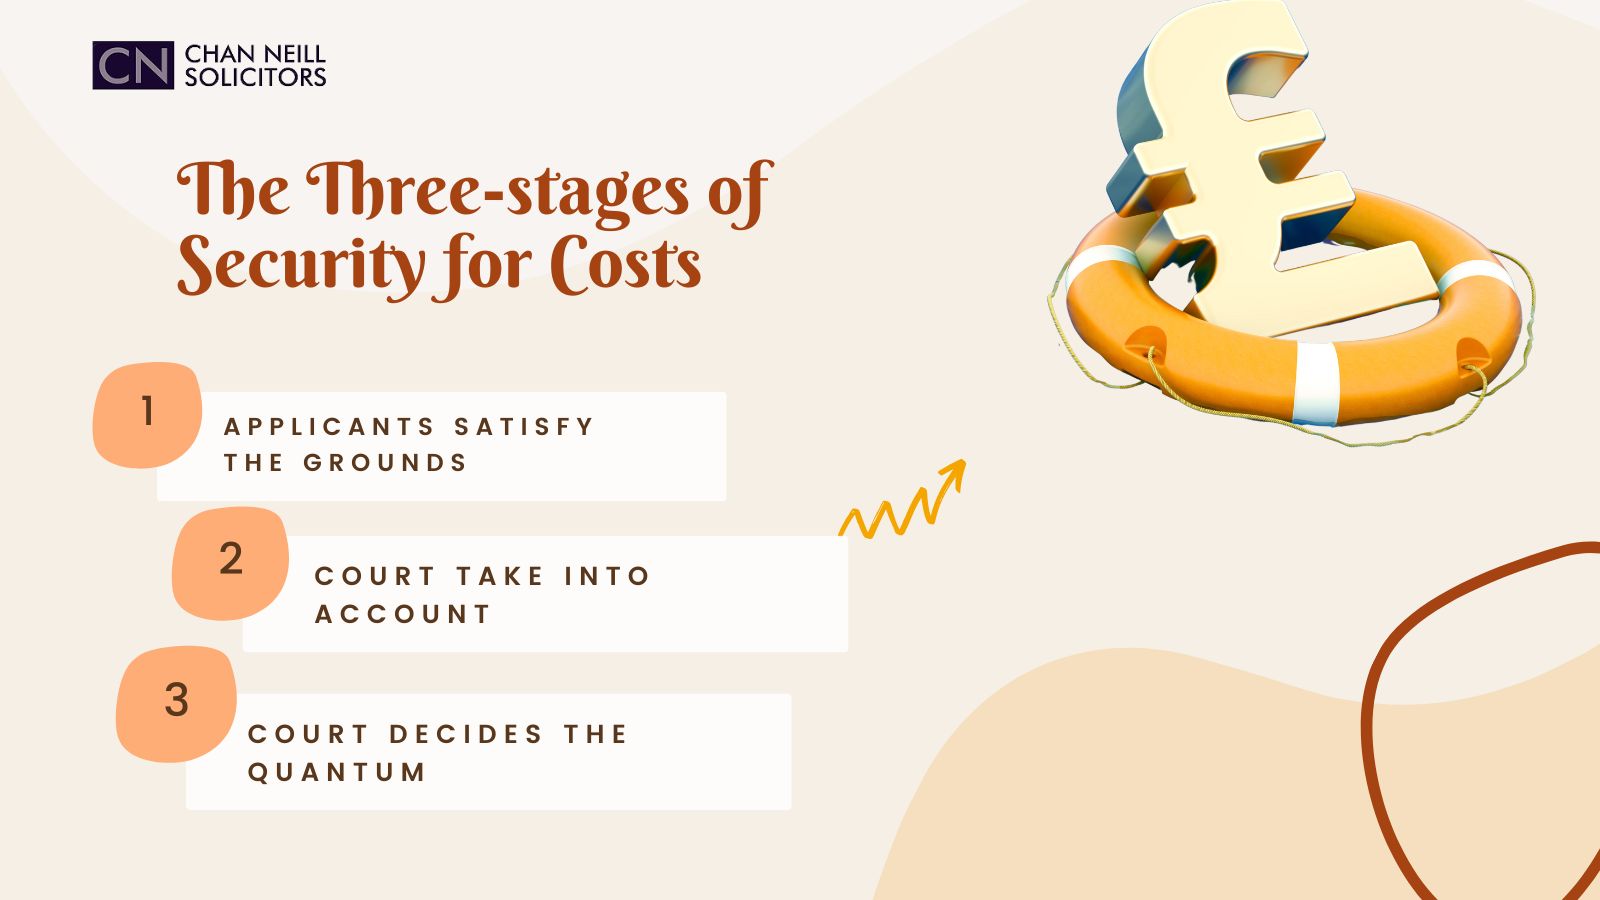
The Three-stages of Security for Costs
What is Security for Costs
Security for costs is an application that a party (Defendant during the proceedings) can make where they believe the other party (the Claimant) does not have the financial means to pay any legal costs awarded to the Defendant should the Claimant’s claim be unsuccessful at trial.
Who can apply for Security for Costs
Usually, an application for security for costs is made by a Defendant, however there are some circumstances where an application can be made by the Claimant (i.e. if the Defendant has made a counterclaim).
The 3-stage process that the Court consider
When the Court considers a security for costs application, there are three stages which are as follows:
- Grounds for Security for Costs
- Whether the Court should exercise its discretion
- Quantum
Grounds for Security for Costs
There are a number of grounds that the Applicant (the person making the application) must satisfy in their application (but not limited to) such as:
- Whether the Respondent resides outside of the UK (or is not a resident in a State bound by the 2005 Hague Convention)
- The Respondent’s address is incorrectly stated on the claim form
- The Respondent’s address is omitted from the claim form
- The Respondent has changed their address during the proceedings with the intention to avoid the cost consequences of the court proceedings.
What the Court’s take in to account
Applications for security for costs are usually dealt with at a hearing. The Court will consider all the relevant factors but not limited to the following points to decide whether the Court should exercise its discretion:
- Whether the grounds for Security for Costs have been satisfied
- How long the Applicant took to make the application
- The financial position of the Respondent
- The implications on the Respondent if an order for Security for Costs is made
- All circumstances of the case
- Whether the Respondent has After The Event insurance
Quantum
Once the court has decided that the grounds have been satisfied and that they should exercise their discretion to grant an order for security, the Court will then consider the amount of security and what form the security should be given.
Usually, the Applicant would request 100% of all their anticipated legal fees set out in their application (cost budget) however the court would review the Applicant’s anticipated costs and exercise their powers to assess the Applicants costs (like detailed assessment).
Conclusion
A party can make an application for security for costs at any stage during the court proceedings however, the earlier the application is made the better.
An Order for Security for costs is discretionary and the court would take in to account the time it has taken for the party to make such application which of course can have a detrimental effect on the court’s decision.
This article is provided for general information only. It is not intended to be and cannot be relied upon as legal advice or otherwise. If you would like to discuss any of the matters covered in this article, please contact us using the contact form or email us on reception@cnsolicitors.com

Artificial Intellegence – a conveyancer’s friend or foe
Technology's influence has been reshaping traditional practices for generations. Conveyancing is no different and conveyancers are now having to come to terms with the integration of artificial intelligence (AI). AI is transforming conveyancer’s day to day working lives. It is changing how conveyancers obtain search results, conduct due diligence, ensure security and navigate regulatory complexities. However, whilst the use of AI can be used as a force to enhance the industry’s effectiveness, there will always be those who see opportunities to fraudulently manipulate technology and AI is certainly no exception.
The conventional process of gathering search results has often been hindered by delays and cumbersome data retrieval. AI is changing this narrative by swiftly scanning and sorting through large volumes of data. AI expedites the extraction of pertinent information, providing conveyancers with a comprehensive overview in a fraction of the time it used to take. This acceleration not only reduces waiting times but also allows for prompt decision-making, a crucial element in the time-sensitive world of property transactions. AI's integration into the realm of conveyancing is not only accelerating the acquisition of search results but also reshaping our approach to information retrieval.
Due diligence, a crucial phase of any property transaction, has traditionally involved laborious manual searches through extensive volumes of data. AI has revolutionised this process by rapidly scanning large datasets to reveal any point of note associated with a property, its owners, and its prospective owners. By automating this data intensive task, AI accelerates due diligence timelines and reduces the risk of crucial information ever being missed. Conveyancers can now offer clients a more efficient and comprehensive due diligence process, enhancing trust and the speed of transactions.
Navigating the intricate network of regulatory compliance and legislative changes is a challenge faced by all legal professionals, and particularly for those working within the everchanging frameworks of property related regulations and legislation. AI allows conveyancers to constantly monitor amendments, to keep pace with changing regulations and legal requirements. Conveyancers can rely on AI to stay up to date with the latest guidelines and legislation, ensuring that every transaction adheres to the highest standards of legality as well as ethical practice. This insight provided by AI offers conveyancers a sense of assurance that their transactions remain compliant in a constantly changing regulatory landscape.
The incorporation of AI into conveyancing is not just about expediting processes; it's about improving the entire experience for both conveyancers and clients. AI's speed in gathering search results, its predictive abilities in risk assessment, its ability to streamline due diligence, and its ability to help ensure regulatory compliance are helping the industry toward a future marked by efficiency and accuracy. As AI continues to evolve and integrate seamlessly into conveyancing practices, the industry is in a position to offer an even higher standard of service and assurance to those navigating the intricate world of property transactions.
Like many industries at this point in time, the advantages AI provides conveyancers must be met with caution. Whilst AI has emerged as a powerful tool with the potential to revolutionise the field of conveyancing, it also brings forth its own set of threats that must be carefully considered.
One concerning aspect is the emergence of AI-powered fraud schemes. As AI technology becomes more sophisticated, criminals will exploit it to create intricate and hard-to-detect fraudulent activities. AI-driven algorithms can generate fake documents, impersonate identities, and manipulate data, posing significant challenges to traditional fraud prevention methods.
The vulnerabilities in cybersecurity cannot be ignored. AI systems themselves can become targets of cyber attacks. If fraudsters manage to compromise AI algorithms or access crucial data, they can leverage the technology against the very systems meant to safeguard against fraud, potentially exposing sensitive client information.
Recently, fraudsters have been able to use public data leaks to use AI algorithms in order to comb through email accounts involved in leaks. The criminal’s algorithms will identify those accounts containing emails with key-words associated with property transactions. Once identified, the fraudsters will target said accounts, the accounts of property purchasers more often than not, with emails enticing purchasers to send funds to fake client accounts. Whilst clients may recognise that something is not quite right with the emails, the importance of personal relations is evident here. A client having full knowledge of their transaction, knowing that this may be a strange time to send funds, will prevent them from ever doing so.
Another critical consideration is the issue of human oversight. Although AI excels at processing vast amounts of data and recognising patterns quickly, it lacks the nuanced judgment and intuition inherent in an experienced conveyancer. Relying solely on AI systems for fraud prevention may lead to false positives, flagging legitimate transactions as fraudulent, or false negatives, overlooking genuine instances of fraud. AI algorithms learn from historical data, which can contain implicit biases. This can inadvertently lead to discriminatory practices, where certain individuals or properties may be unfairly targeted or excluded from transactions based on historical patterns.
Additionally, legal and ethical challenges come to light with the adoption of AI in fraud prevention. Determining accountability and liability for AI related fraud can be complex, raising questions about who bears responsibility when an AI system fails to prevent fraudulent activities is a fresh issue the industry does not have a definitive answer to.
To address these concerns, it is essential to strike a balance between implementing the advantages of AI and the significance of human involvement. Combining AI systems with human expertise and judgment can ultimately enhance the overall effectiveness of fraud prevention measures.
Looking to the future, there is of course a risk of overreliance on technology. The convenience and efficiency that AI brings might inadvertently lead professionals to become complacent in detecting potential fraud when they overly rely on AI systems to handle the task. Combining this with the use of AI by fraudsters themselves and there is certainly cause to be cautious of AI and its impact on the conveyancing process.
Legal work will always be an industry which requires a human touch. Clients rely on a conveyancers personal experience and person ability in the same way they rely on their skills in dealing with the law. Incorporating AI into the world of conveyancing has to be a conscious process which considers all advantages and disadvantages. As always, the client, their goals and their experience, will remain at the heart of all legal work. Conveyancing is no different.
Account Freezing Order
What is an account freezing order (AFO)?
An AFO is an order granted by the Magistrates Court to freeze a bank account in the UK. This order is usually applied for by an enforcement officer, such as the police, if they have suspicion that the monies on account are part proceeds of criminal activities or intended for illegal purpose. The most common event is a large sum of monies transferred into a bank account or multiple deposits of cash into a bank account in a short period of time.
A common case
In a common scenario, you will first notice that you suddenly have no access to your bank account via mobile banking or online banking, or your balance in your account becomes zero. When you call the bank they may tell you that they are unable to deal with this or provide any information.
Shortly after, you either receive an AFO from the police or a notice of application for AFO from the court.
The threshold for the initial AFO application is quite low and the court is likely to grant it for an initial period of time.
Period of AFO
Once the AFO is granted, it would be subject to a period of time for the police to undertake the investigation as well as for you to provide an explanation and all evidence. The period of an AFO varies depends on the complexity of the case. The most common AFO lasts 6 months. If 6 months is not enough for you to the provide evidence or for the police to conduct the investigation, it could be extended up to 2 years.
Variation of an AFO
In the case that all monies that you could utilise are frozen in that bank account or you would need them for some urgent matter, you are entitled to make an application to the court to vary the AFO. You will need to demonstrate your reasonable living expenses and / or the urgency of the matter. You can also make application to pay your legal expenses from the frozen money.
Investigation
As mentioned above, during the investigation the police will ask you for an interview to answer questions they have or provide a written explanation of your funds. It is usually advisable to seek independent legal advice at this point before responding to the police. The main aspect is to give proper explanation for the funds in your bank account. For example, if some monies are your salary, you may need to provide your employment contract/pay slip or a confirmation from your employer if necessary to show that these monies are your rightful gain.
Possible results
If the police are satisfied with the clean source of funds, they will make another application to the court to set aside the initial AFO. Once the court approves that the police will inform the bank to unfreeze the account and release the monies to you.
It is also possible that, after the investigation, the police may decide to apply for the relevant amount or all of them to be forfeited, if they think those funds are the proceeds of crime. They will serve you a notice and you could raise an objection within a certain time period. If objected, you will need to make an application to set aside such forfeiture, the case will then proceed to the court for the judge to decide whether the forfeiture should be granted. You can seek legal advice for further details.
It is also open to you to apply to discharge the AFO if there are sufficient grounds
Seek legal advice
It is important to seek legal advice as soon as possible once you receive an AFO. Chan Neill Solicitors can provide expert guidance on the procedure and the best approach for your case. By assessing the validity of the AFO and carefully reviewing the evidence and circumstance surrounding the case, we can offer a variety of tactics to ensure the most favourable outcome for your case.
Financial Remedy
What is a Financial Remedy Order?
When a married couple petitions to divorce in the UK, they need to also resolve relevant financial issues. This is commonly referred to as financial remedy proceedings, with a Financial Remedy Order. This is a process by which a couple's assets and income are divided upon divorce or separation. The objective of financial remedy is to provide a fair and reasonable financial settlement between both parties.
Application
The procedure for financial remedy in the UK begins with an application to the court. The application form is called Form A. This application can be made by either party involved in the divorce or civil partnership dissolution. The application is made to the family court, which has the jurisdiction to hear and decide such cases.
First Appointment
Once the application is received by the court, the first step is to arrange a hearing to determine how to proceed with the case. At this hearing, the court will consider whether there is a need for further hearings and what type of financial remedy order is required.
The next step is to gather all relevant financial information from both parties. This includes assets, income, and expenses. Both parties are required to provide full disclosure in a Form E of their financial situation, including any debts, savings, pensions, and other assets. Both parties may raise questions regarding the disclosure. If a property is involved, the court may order to instruct an expert on valuation and tax issue. Failure to provide full disclosure can result in the court imposing a penalty.
Both parties shall exchange their proposals/offers to settle their case before the next hearing.
Financial Dispute Resolution Hearing (FDR)
If no settlement is reached, FDR will happen. The main objective of an FDR hearing is to encourage parties to reach an agreement on financial matters before proceeding to a final hearing, which can be expensive and time-consuming. The FDR hearing is an important stage in the financial remedy proceedings as it provides an opportunity for both parties to have a frank discussion and negotiate a settlement.
At the FDR hearing, the judge may provide an indication of how they would likely decide if the matter proceeded to a final hearing. This is intended to encourage parties to make a realistic settlement offer that is in line with what the judge might decide at a final hearing. If parties reach a settlement at the FDR hearing, it will be recorded in a legally binding court order, which can be enforced in the future.
Final Hearing
The Final Hearing is the last stage in financial remedy proceedings in England and Wales. It is where the parties present their evidence and legal arguments to the judge who will then make a final decision on how the couple’s assets will be divided. It is important to note that the vast majority of cases are settled before reaching the Final Hearing stage, either through negotiations or via alternative dispute resolution methods such as mediation or arbitration. However, if the parties cannot come to a mutual agreement, then the Final Hearing will be the final chance to make their case.
During the Final Hearing, each party will have the opportunity to present their case to the judge, including calling witnesses if necessary. The judge will then make a final ruling, taking into account all the evidence and legal arguments presented. The Final Hearing is a crucial part of the financial remedy process and it is important for both parties to prepare thoroughly to ensure the best outcome.
Conclusion
Financial remedy can be a complex and challenging process, and it is essential to seek legal advice from solicitors who have excellent knowledge and experience in family law.
What Is Pre-nuptial Agreements?
A pre-nuptial agreement (“Pre-nup”) is a legal agreement made between two parties before they get married. Usually, the agreement specifies how the couple wish to split their assets in the event of separation or divorce.
You can also use a Pre-nup if you are planning to enter into civil partnership – although they are often referred to as pre-registration agreements.
Should you get a Pre-nup?
It is very common to think that a Pre-nup is just for wealthy people, such as business people or celebrities who wish to protect their assets. Such an agreement can make sense when one half of the couple has significantly more assets than the other, he/she stands to lose more than the other in an equal split divorce settlement.
However, in the case where neither of the couple have significant fortunes before getting married, they could still wish for a Pre-nup if either / both of them is / are expecting significant further earnings.
Furthermore, should you anticipate receiving gifts of large value (for example, a property gifted by your parents) or there is an inheritance to protect before the marriage, it may be a good idea to consider making a Pre-nup.
Is Pre-nup binding in the UK?
Short answer, no.
Pre-nup is not legally binding, which means that in an application for financial remedy, the court would have absolute discretion ( based on needs and contribution to the marriage ) to decide how to distribute the parties’ assets regardless of the contents of the Pre-nup.
However, if the agreement has been properly drafted, the court will give appropriate weight to it and the parties intentions when assessing an application for financial remedy. If a Pre-nup is drafted properly and no details of assets are left out by either party, it is often the case the court will accept all the terms of the Pre-nup that the party agreed to. To be more precise, the court is more likely to uphold a Pre-nup that is freely entered into by both parties with a full appreciation of its implications and all assets and monies are listed fairly.
Pros of a Pre-nup
It is quite self-explanatory that one of the biggest pros of getting a Prenup is to protect your assets that you have now or will have in the future.
Furthermore, in the case that your partner has significant debts (or likely to incur significant debt in the future), a Pre-nup could be used to protect your assets from being used to satisfy those debts.
It would incur some legal fees for solicitors to draft and advise on a Pre-nup. However, in an unfortunate and unpleasant divorce, a Pre-nup could save you significant stress and further expense, if both parties adhere to the terms of the prenup, during separation and divorce.
In addition, it could be you have concerns that your partner may be marrying you due to your wealth. If your partner agrees to enter into a Prenup with you that leaves you both with fair and reasonable financial terms, this may actually it ease your mind and strengthen the bonds of trust as you enter marriage.
Cons of a Pre-nup
As mentioned above, it is not legally binding, but persuasive to a court.
Also, trying to negotiate the terms of a Pre-nup may be awkward with your partner. It may be something they are unwilling to discuss or enter. It is always best to be open about the reasons for suggesting same. This may still cause a barrier between you.
Additionally, it could be the case that it is the parents of the economically stronger party pushing the couple into making a Pre-nup. A Pre-nup can end up reflecting the parents' wishes rather than the couple's wishes. In this regard, the behaviour that amounts to duress and undue influence may result in little (or no) weight being placed on the Pre-nup in any future financial remedy proceedings. To safe guard against this risk, usually both parties should have separate lawyers representing them.
The future of Pre-nup
On 27 February 2014, the Law Commission published a report recommending the introduction of qualifying nuptial agreements that will limit the court's powers to make financial orders on divorce or dissolution. The court would be prevented from making orders inconsistent with the terms of a qualifying nuptial agreement unless in exceptional circumstance.
To be a qualifying nuptial agreement, an agreement must meet the following criteria:
- It must be contractually valid;
- It must be validly executed as a deed and contain a "relevant statement";
- It must not have been made within the 28 days immediately before the wedding or civil partnership ceremony;
- Both parties to the agreement must have received disclosure of material information about the other party's situation when they entered into the agreement; and
- Both parties must have received legal advice at the time they entered into the agreement.
This is a recommendation to the judiciary, but the intention is clear that unless the Pre-nup is unreasonable and unfair to one of the parties that entered it, the court should be persuaded that these terms agreed to are sanctioned.
Please contact our experienced family law team if you have any questions about pre-nuptial agreements or matrimonial-related enquiries. Our team speak several languages beside English including Mandarin Chinese, Cantonese, Portuguese, Russian, Gujarati and Korean.
How Can A Leaseholder Extend Their Lease?
There are two ways that a Leaseholder (Tenant) can extend their lease:
1) Privately Agreed (Informal) Route
2) Statutory (Formal) Route
Private (Informal) Route
The Tenant could approach their Freeholder (Landlord) to request whether the Landlord would be agreeable to negotiate a lease extension. Although this private route could save time and money however, there is no obligation on the Landlord to respond or agree to extend the lease.
If in the unfortunate events that the negotiation discussion between the Landlord and Tenant come to an end without any successful conclusion then the Tenant could consider whether they are able to extend the lease under the Statutory Route.
It is important to note that privately agreed lease extension requires lender’s permission. Therefore, if there is a mortgage registered on the Tenant’s property then the Tenant must obtain the lender’s consent.
Statutory (Formal) Route
A Tenant can apply to extend their Lease by the Statutory Route provided that the Tenant is eligible (such as owned a long lease for the past two years).
The Tenant would need to ensure that they have their finances in place in order to commence the Statutory Route. This is because the Tenant would need to pay for the following:
- Surveyor’s fees to value to a new lease and negotiations etc
- a premium to the Landlord to extend the Lease (once a premium has been agreed)
- Once the Tenant serves a notice to request for a new lease then the Tenant will be liable for the Landlord’s costs
- Landlord’s fees to extend lease
- Solicitors costs etc
The Statutory Route has strict timelines that the Tenant must comply with. If the Tenant fails to comply with the timescales then unfortunately the Tenant would have to wait 12 months before starting the Statutory Route again. There is no requirement for lenders consent under the statutory lease extension route.
Terms of the New Lease
Under the Statutory Rules, the Terms of the New Lease are as follows:
- Peppercorn ground rent (£0 ground rent) for the whole of the term
- 90 years extension plus the length of time left on the current lease
- Terms must be the same except for minor modification and exclusions allowed by law.
- Premium payable for the new lease
S42 Notice – Tenant’s request for a new lease
Before a Tenant can serve a S42 notice, the Tenant would need to identify who the competent Landlord is. The Tenant should apply to the Land Registry to find out who owns the Freehold Property and check who they pay their service charges and ground rent to.
If a Tenant pays ground rent and or services charges to a management company then all parties (Landlord and Management Company as well as any other relevant person) should be served with a copy of the S42 Notice.
The S42 Notice must contain certain information in order for it to be valid. The Tenant must give the Landlord at least two months to give their counter-notice.
The Tenant should ensure that the S42 notice is protected by way of registration against the competent Landlord’s Title and also of any intermediate Landlord. Failing to protect the initial notice will not bind a purchase of any reversionary interest in the property and therefore, the Tenant will have to start the process again.
S45 Notice – Landlord’s Counter Notice
The Landlord must serve their counter-notice within the 2 months period. The Counter-notice must state one of the following:
- Agree to the Tenant’s right to a new lease and accept the terms and proposed or propose different terms
- Reject to the Tenant’s right to a new lease and explain their reason for this.It would then be up to the Court to decide whether the Tenant has the right
- Claim that the Landlord has the right to redevelop the land (appliable only in certain circumstances)
If the Landlord has served a Counter-notice then it would be down to the parties surveyors to negotiate on a premium. If in the unfortunate event that an premium cannot be agreed after the first two moths of negations, then both parties can apply to the Tribunal for an independent decision to be made. The application must be made within 6 months from the Landlord’s counter-notice.
Once a premium has been agreed then the parties legal representatives can negotiate on the terms of the lease. There are strict timelines on when the new lease terms must be agreed and when a claim must be made to the Tribunal.
In the event that the Landlord fails to serve a counter-notice, then the Tenant has the right to apply to the Court to seek an order for the grant of the new lease (on the terms as set out in the S42 Notice). This application must be made within 6 month from the date in which the counter-notice was required to be served.
If you are thinking of extending your lease or have any queries, please contact us. Our experienced property solicitors and litigation team have dealt with different types of lease extension.
Is Your Tenant In Rent Arrears?
Occasionally Landlords will have Tenants who complies with the terms of the tenancy agreement and pay the rent on time with no issues.
However, in the unfortunate event that a Landlord has to deal with a Tenant who defaults on the rent payments then the Landlord may wish to consider the options available to them. Whilst Landlords tend to own the property that they rent out a Landlord cannot simply kick the Tenant out, there is a process that the Landlord need to follow.
Enter in to Negotiation discussions with the Tenant
A Landlord should try and speak to their Tenant if the Tenant is in breach of any of the terms of the tenancy. Any verbal communication should be followed up in writing to ensure that there was no misunderstand.
If the Tenant is in rental arrears then the Landlord may consider whether they would be agreeable to a repayment plan or seek the Tenant’s consent to deduct the outstanding rent from any deposit that is being held in a deposit scheme. Sometimes communication with Tenants does not always work and therefore, this would leave the Landlord with the only option but to issue court proceedings to regain possession of the property.
Monetary Claim
The Landlord could issue a money claim against the Tenant for the rental arrears. There are set proceedings that the Landlord must follow i.e. complying with the pre-action protocol and sending a letter before action.
If the Tenant fails to respond to the letter before action then the Landlord can then issue a monetary claim against the Tenant.
Eviction Claim
There is a 3 stage process to eviction claims for both Section 8 (breach of tenancy) and S21 Route (possession and money judgment / possession only) which are set out below:
Section 8 Route - breach of terms of the tenancy
- Notice
Where a Tenant is in breach of the terms of the Tenancy or in rental arrears then the Landlord can prepare a Section 8 Notice giving the Tenant a certain length of time to rectify that breach.
- Issue Court Proceedings
If the tenant fails to pay the arrears or rectify the breach then the Landlord can issue possession proceedings.
The Landlord have the option to issue proceedings online via possession claims online if the breach is only in relation to rent arrears. There is a court fee of £355. The court will issue the claim and if the Landlord has provided the Tenants address within the claim form then the Court will serve the claim on the Tenants. The Tenant will have 14 days to respond to the claim. The Court will also list the matter down for a hearing.
Section 21 Route - no fault possession
- Notice
Landlord must give the Tenant at least 2 months’ notice to vacate. This route has become stricter in a sense that there are a number of obligations on a Landlord that must be fulfilled in order to use this route.
- Issue proceedings
There are two options which a Landlord could take which are as follows:
- Standard Route: The process is similar to issuing proceedings under the Section 8 route as a hearing date will be listed. A Landlord can use this route for possession and also a monetary judgment for the rental arrears.
- Accelerated Proceedings Route: this route can only be used if the tenancy agreement is in writing and all the Landlord's requirements are fulfilled (i.e protecting deposit, serving EPC certificate, served Gas Safety, How to rent booklet on the Tenant). The Accelerated Route is only available for possession only. This means that the Accelerated Route cannot be used if the Landlord wants to seek possession and also a monetary judgment for the rental arrears.
- Instruct Bailiffs
Once an Order for Possession has been granted (regardless whether it has been made under the Section 8 Route or the Section 21 Route), the Landlord can instruct County Court Bailiffs or apply to the County Court to obtain permission to instruct High Court Enforcement Officers. The Bailiffs will then arrange an appointment date to attend the property to lawfully evict the Tenant.
If you are dealing with a "difficult" tenant or facing rent arrears, please contact our experienced litigation team.
Rights As A Tenant In A Private Rented Property
A tenancy agreement sets out the rights and responsibilities between the landlord and tenants. In the unfortunate event where an issue arises then the tenants should refer to the tenancy agreement. Tenants have additional rights which are not always set out in the tenancy agreement. To give an example, the House in Multiple Occupation (HMO) licensing.
We have set out below the key points that tenants should be aware of when renting a property.
Additional fees
The Tenant Fees Act came into force on 1st June 2019 and the centre of this rule is that it prevents landlords from charging tenants with extortionate fees. The landlords are allowed to charge the tenants rent, tenancy deposit, and or a holding deposit.
Under the Tenant Fees Act, landlords are no longer allowed to charge tenants the cost of their own references or police checks, general administration fees, or cleaning fee. Landlords who charge fees that fall outside of the Tenant Fees Act may be liable to pay a fine of £5,000 however if the landlord repeats the breach, then this could lead to a criminal charge or a fine of £30,000.
However, the landlord can charge certain fees provided that it is written into the tenancy agreement, these are set out below:
- Late Rent Fees
Landlords can charge fees for rent payments that are due over two weeks. The fees can be charged up to 3% plus the Bank of England base interest rate.
- Default Fees
This includes the tenant losing a key or damaging the property. The tenant can only be charged a reasonable amount as long as the evidence of the cost can be provided.
- Changes to Tenancy Fees
Landlords can charge up to £50 for making changes to the terms of the tenancy agreement. This can include changing a tenant’s name or allowing a pet.
Disrepair
Under section 11 of the Landlord and Tenant Act 1985, landlords have the obligation to keep
the property in a habitable state for the tenants to reside in. This includes heating, hot water, access to power supply, water, etc.
These repair obligations cannot be changed by any terms written into the tenancy agreement and landlords cannot charge tenants for any repairs that fall under their mandatory obligations.
However, tenants would usually be responsible for the maintenance of the property. This includes the general upkeep such as changing the lights, unclogging sinks, gardening, and cleaning.
Should a tenant experience any disrepair issues such as mould, no heating, no hot water, etc then they should first report this to the landlord immediately.
If the landlord refuses to carry out the repair works then the tenant has various options available to them such as reporting to the local council and or issuing proceedings against the landlord.
House in Multiple Occupation License
The Housing Act regulations ruled that an HMO license is required for any house or flat that is occupied by five or more people who are not all related and live in the property as their main home. Landlords are therefore obliged to apply for a license application at the local council if the property needs licensing.
Ignoring the rules would result in the landlords paying a heavy price. There would be a risk of being prosecuted by the council and if found guilty landlords could get a criminal record, and be fined an unlimited amount. Alternatively, tenants can apply for a Rent Repayment Order and the landlord may have to repay up to 12 months of rental income.
Deposit
Deposits were collected as part of the renting process and landlords are obliged to pay the tenants’ deposits into a deposit protection scheme. This deposit protection was introduced on 6 April 2007 as part of the Housing Act 2004 and these protection schemes offer a free service to help resolve deposit disputes between the landlords and tenants.
When a deposit was not protected under a scheme and no further information was provided by the landlord, tenants can apply to the County Court for an order that the landlord returns the deposit back or protect it under one of the tenancy deposit protection schemes.
There are rules on what costs can be deducted from the deposit. And the landlord cannot, in general, charge for the costs of maintaining the wear and tear of the property. The usual costs can include deductions for (1) damage to the property and missing or broken items, (2) cleaning fees, and (3) unpaid rent or bills.
If tenants disagree with how the deposit is returned, or the tenant does not agree with some of the costs that landlords have taken out of it, tenants must ask the landlord for a breakdown of the specific costs which were taken out of the deposit.
In the case where an agreement could not be reached between the landlord and tenant, the parties can propose to use the free alternative dispute resolution service offered by the tenancy deposit scheme.
Under the alternative dispute resolution service, the parties are required to accept the decision made and will not be able to apply the decision to the courts. If on the contrary the landlord or tenant does not agree to use the dispute resolution service, then the dispute will usually go to the County Court.
If you require assistance in relation to private renting disputes, or you would like to learn more about the rights and obligations shared between landlords and tenants in private properties, please feel free to contact us and we can discuss and advise on your best way forward.
New Divorce Laws - "No-Fault" Divorce
New Divorce Laws - "No-Fault" Divorce
The Divorce, Dissolution and Separation Act 2020 came into force in England and Wales on 6 April 2022 and this signified a major development of England’s divorce laws for the past 50 years.
Key changes made under the new Act:
- The need for the married couple to prove the irretrievable breakdown of marriage by citing grounds of unreasonable behaviour and separation was replaced by a sole or joint statement.
- The statement of irretrievable breakdown of marriage serves as a piece of conclusive evidence for the court to make an order and this prevents a spouse from contesting the divorce.
- A minimum period of 20 weeks between the start of divorce proceedings and the application for conditional order was introduced.
- New language has been adopted to facilitate a better understanding of the divorce application.
Referring to the first point, the new divorce application introduced a “no-fault” basis which completely replaced the requirements under the previous divorce laws. This is because the previous divorce laws required divorcing couples to prove the irretrievable breakdown of their marriage by citing one of the five existing grounds, these can be referred to as:
- Adultery
- Unreasonable behaviour
- Dissertation by one party
- Two years separation with the consent of the spouse; or
- Five years separation without consent
The previous divorce laws made it difficult for married couples who wanted their divorce to be settled in the most peaceful and straightforward manner. This is because the previous rules adopted a “blaming” basis and therefore couples looking to divorce must either put a blame on one another for the breakdown of their marriage or they must carry out a long-term separation to satisfy the requirements. Inevitably, this caused unnecessary stress and animosity which in turn encouraged potential conflicts between the divorcing parties.
Under the new divorce laws, couples can sign a sole or joint statement of irretrievable breakdown of the marriage to begin the application. This completely removes the need to blame each other or to give reasons for the breakdown of the marriage. Except for certain exceptional grounds, the statement also prevents a spouse from contesting /defending the divorce petition as it serves as a piece of conclusive evidence.
The new rules also introduce a new minimum period of 20 weeks between the start of the divorce application (signing the statement) and the application for the conditional order. When the conditional order is granted by the court, there is another period of 6 weeks before we can apply for the final order of divorce. This change effectively provides the divorcing parties a period to reflect and reconsider their decisions. However when a divorce is inevitable, this also allows the parties time to plan and cooperate on the practical arrangements surrounding the divorce such as financial and children matters.
A change in divorce law has been long-awaited as many would think the previous laws to be outdated, simply increasing animosity and stress in already difficult circumstances. However, the law in respect of financial provision for divorce will remain the same.
We at Chan Neill Solicitors relate to the emotions and stress often involved during the divorce proceedings and our experienced Civil Litigation team can assist in guiding you through every step of the divorce process. Please contact us and we can discuss your best way forward.
What should I do if I get into a car accident with a uninsured driver in the UK?
What should I do if I get into a car accident with a uninsured driver in the UK?
‘Have you been involved in a road traffic accident that isn’t your fault?’ This is a familiar question that we often hear from adverts. However, what happens if you were involved in a road traffic accident with a driver that was not insuredin the UK? In the absence of the insurers for the responsible party, is it still possible to make a claim and possibly get compensation for your injuries resulted from the accident?
The Motor Insurers’ Bureau are a non-profit-making company set up by motors insurers, who have entered into agreements with the UK government to compensate victims of motor accidents caused by uninsured drivers. The Road Traffic Act 1988 requires that every motor insurer must be a member of the MIB and must contribute to the funding of the MIB. The time limit to submit a claim is the same as road traffic accident claims against injured drivers – within three years of an accident if claiming for personal injury. In the case of injury for children, the three year time limit commences on the 18th birthday.
On the claim form, the MIB will ask you to provide details to learn more about your involvement in the accident, details of the parties involved, details of the accident, details of police involvement, witnesses, details of your claim, and any associated personal injury as a result of your accident.
Once the claim has been submitted to the MIB, you or your legal representatives will be contacted and an investigation will commence. The investigations by the MIB are to establish the facts, confirm the identity of the parties involved, obtain independent reports from motor engineers or witnesses, obtain a police report, and contacting other bodies such as the DVLA, your insurer, or a foreign bureau. If you are claiming for personal injury, the MIB may need to obtain copies of your medical records from your GP and hospital you attended after the accident. The MIB may also need to obtain an independent medical report to assess your injuries caused by the accident.
The MIB will compensate you once a causal link is established between your injuries and the negligence of the driver that you consider responsible.
Many solicitors provide services on a conditional fee agreement (also known as a “no-win-no-fee”) basis, which means you only have to pay for the legal services if your claim succeeds. For example, at Chan Neill Solicitors LLP, subject to conditions and eligibility, we take on no-win-no-fee cases for personal injury claims.
Chan Neill Solicitors LLP is one of the leading law firms in London which houses an established Personal Injury practice. Our experienced team of lawyers can offer specialist advice and provide solutions. If you would like to learn more about our Personal Injury practice, please visit https://www.cnsolicitors.com/practice-areas/personal-injury/.
If you have any enquiries, you can fill in and submit the contact form at https://www.cnsolicitors.com/contact-us/. You can also contact reception at 020 7253 7781.